Investors largely expect the Federal Reserve to hold interest rates steady at its October meeting. But a change in how the Fed chair communicates could make that expectation less dependable than it looks, and that matters for apartment owners with loans coming due or floating-rate debt.
What the Market Is Pricing In
On Friday morning, futures markets implied roughly a 15% chance of a rate increase at the October meeting. Several senior Fed officials have voiced support for keeping rates where they are, which gives traders further reason to expect a pause.
Why the Chair’s Approach Adds Uncertainty
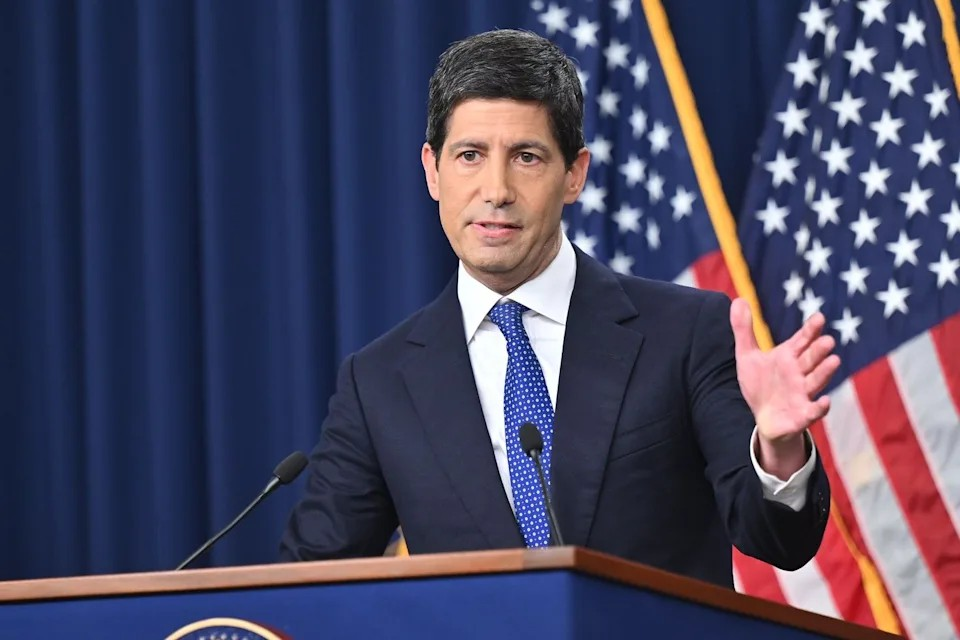
Fed Chair Kevin Warsh has been reluctant to give advance signals about policy decisions, and he has stressed that other officials’ views do not determine his own position. Speaking at an International Monetary Fund event in Bangkok on Friday, he said his remarks should not be read as pointing toward any particular outcome.
The committee’s decision is set for October 28. Persistent inflation, along with financial conditions that do little to restrain economic activity, could give policymakers arguments for another increase.
What It Means for Apartment Owners
A pause is still the market’s favored outcome, but there is a difference between expectations built on colleagues’ comments and a commitment from the chair. With Warsh keeping his options open, an increase cannot be ruled out. For apartment owners, a few practical points follow:
- Floating-rate loans: Owners with variable-rate debt carry the most direct exposure to a surprise move, since payments can adjust soon after a hike.
- Refinance timing: If a loan matures in the next several months, ask your lender how quotes are structured and how long a rate lock lasts, so an unexpected decision does not catch you mid-process.
- Debt service coverage: Run your numbers at a higher rate now. Knowing how much cushion you have makes any decision easier.
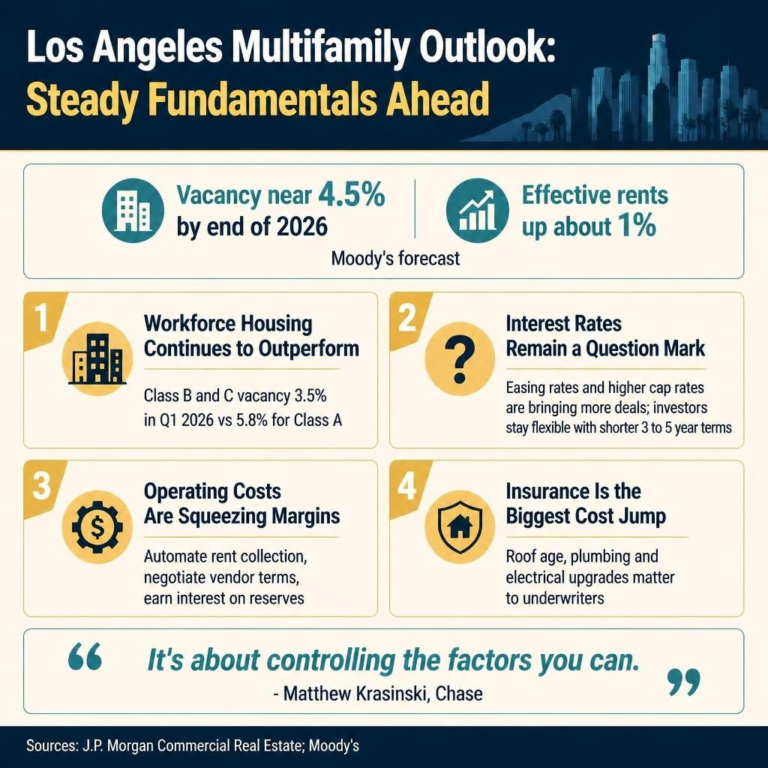
- Flexibility: Many investors are favoring shorter loan terms and keeping options open while the rate path is unclear.
The Bottom Line
The base case is a pause, but the October 28 decision is less certain than the market’s pricing suggests. If you are weighing a refinance, a sale, or a purchase, the next few weeks are a good time to review your loan terms and test your numbers against a higher-rate scenario. I’m happy to talk through how this affects your property.